Brazil has strategic mineral resources beneath its soil. Rare-earth elements help make permanent magnets, electric motors, wind turbines and electronic equipment. Yet the country’s considerable geological potential contrasts with the relatively small scale of its current production.
Understanding why Brazil has so many rare earths but produces so little begins with a simple distinction: identifying a mineral occurrence is only the beginning. Turning that discovery into a business requires research, permits, capital, infrastructure and processing capability.
What do Brazil’s official 2025 figures show?
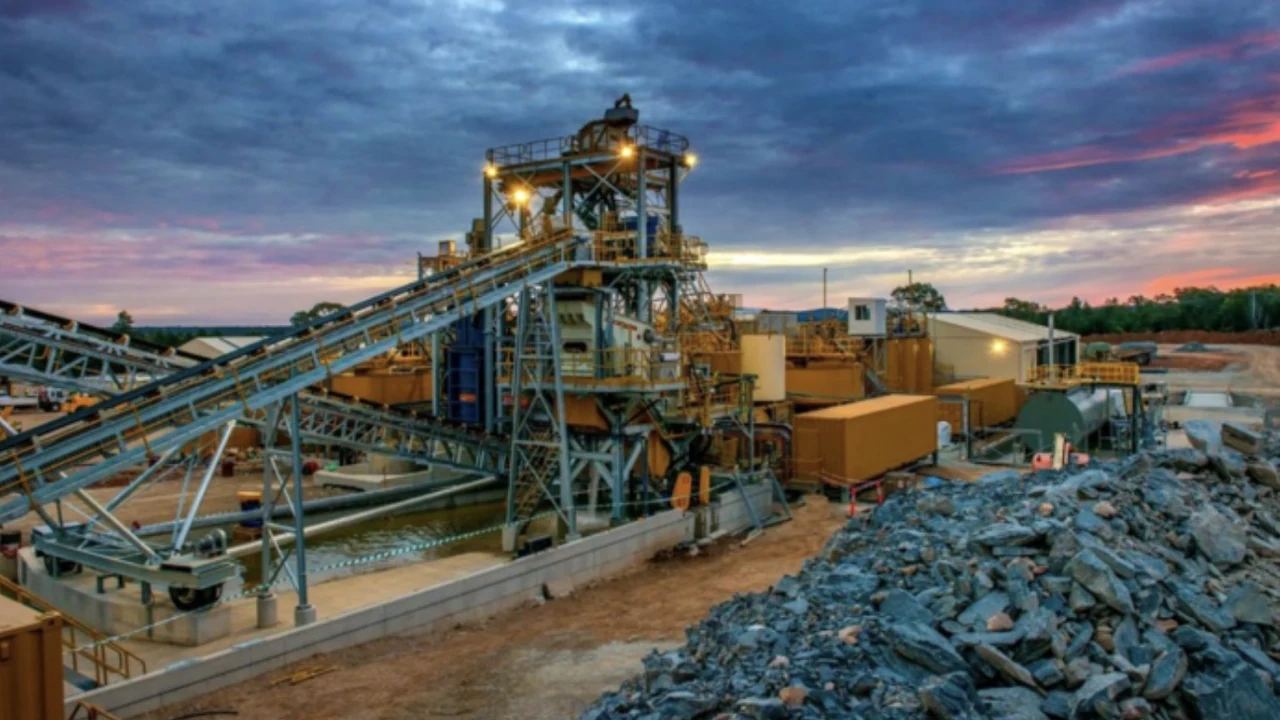
In a report published on October 14, 2026, the National Mining Agency (ANM) said Brazil produced 326 metric tons of rare-earth oxide concentrate in 2025. It identified four active mining areas, all in Goiás state.
The agency also recorded 3,067 areas under mineral exploration, 78 areas at more advanced stages of mining-rights applications and 75 locations identified as having potential by the Brazilian Geological Survey. These figures refer to different stages of development. Exploration authorization is not a commercial mining operation.
On trade, ANM reported US$14.9 million in concentrate exports and US$30.6 million in imports of processed products, including oxides and magnets, in 2025. The categories illustrate activity at different points in the industrial chain. They do not establish the value added in each stage or provide a comprehensive rare-earths trade balance.
Where are Brazil’s rare-earth reserves?
ANM’s Brazilian Mineral Summary 2025, drawing on revised 2024 data, gives a reserve estimate of 11.4 million metric tons. It identifies occurrences in Goiás, Minas Gerais, Amazonas, São Paulo and other states.
Important geological areas include Minaçu and Catalão in Goiás, Araxá, Poços de Caldas and Tapira in Minas Gerais, and Pitinga in Amazonas. These are geological references, not a list of operating rare-earth mines.
Resources, economically recoverable reserves, exploration areas and commercial output have different meanings. A promising deposit can still require years of testing before production begins.
Why is extracting ore only one part of the business?
Rare earths comprise 17 chemical elements. They may occur in ores and clays with different concentrations and geological characteristics, which affect how economically a deposit can be mined.
After mining and beneficiation, industrial operators must separate elements with very similar chemical properties. Refining, metal production, alloy-making and magnet manufacturing require additional technology, facilities and specialist expertise.
This helps explain how a country can hold substantial reserves yet import sophisticated manufactured products. The location of the mineral deposit does not determine where chemical plants, technology suppliers or magnet factories will be built, nor who captures most of the commercial value.
What is preventing faster production growth?
Barriers emerge across the project lifecycle: deposit characterization, economic feasibility, environmental licensing, energy and water availability, transport infrastructure, funding, specialized chemical processes and commitments from customers.
Interest is growing. ANM reported a 485.4% increase in rare-earth exploration authorizations between 2021 and 2025. That is evidence of stronger exploration activity, not a corresponding increase in operating mines or magnet factories.
Projects should therefore be tracked through verifiable milestones: exploration reports, mining rights, permits, final investment decisions, construction, commissioning and actual output.
What decisions does Brazil face?
For companies, opportunities may arise in mining, oxide separation, refining technologies or component manufacturing. Each link has different skills, financing requirements, business partners and development timelines.
For policymakers, the challenge is to identify which stages can become competitive in Brazil, which need international scale, and how to align investment with environmental oversight and economic benefits for local communities.
The next question is unavoidable: how much of Brazil’s mineral wealth can become Brazilian industrial capacity?
ANM’s open data portal provides a starting point for distinguishing project announcements from recorded results.
Sources and methodology
Production, mining-rights, exploration and trade figures are drawn from ANM’s October 2026 release, with 2025 as the reference year. The reserve figure is ANM’s revised 2024 estimate published in its Brazilian Mineral Summary 2025. Conclusions about industrial capacity are NEODY editorial analysis of the cited evidence.